
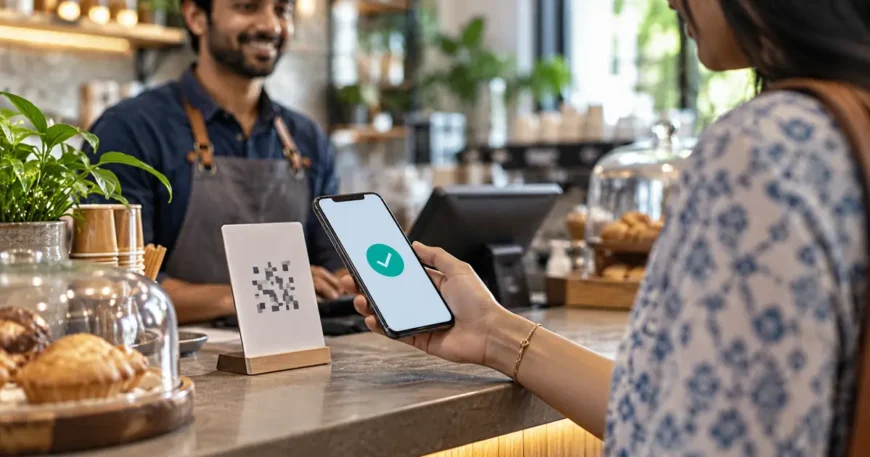
Offering a digital payment option does not automatically create a smooth payment experience. A customer may choose UPI for one purchase, prefer a card for another and use cash when uncertain about connectivity or acceptance.
For banks, payment providers, retailers and consumer brands, the useful question is not simply whether people know about UPI. It is how different customers decide when to use it, what builds confidence and what happens when a transaction does not go as expected.
UPI consumer behaviour research examines these decisions in context. It helps businesses understand the gap between payment availability and a payment experience that customers are comfortable using repeatedly.
What Is UPI Consumer Behaviour Research?
Unified Payments Interface, or UPI, is an instant payment system developed by the National Payments Corporation of India. NPCI provides the official reference point for UPI information and FAQs.
Consumer research focuses on the people using, considering or avoiding this payment method. It examines awareness, onboarding, everyday usage, app preferences, trust, difficulties and recovery after problems.
It also recognises that adoption is not a single event. Registering for a payment service, completing a first transaction and making it a regular habit are different stages. Each stage can involve different barriers and therefore require different business responses.
Why Payment Behaviour Matters to Businesses
A checkout can technically support UPI and still create confusion. Customers may struggle to understand payment status, identify the correct recipient or decide what to do when the merchant has not received confirmation.
These experiences affect more than the transaction itself. They can influence checkout abandonment, repeat usage, support demand and confidence in the merchant or payment application.
Research helps separate problems that require interface improvements from those that involve merchant processes, communication, infrastructure or customer understanding. Without that distinction, a team may redesign a screen when the larger issue is an unclear resolution process.
Factors That Shape UPI Payment Preferences
Convenience in a particular situation
Convenience depends on context. Paying at a busy counter differs from completing an online order or transferring money to someone familiar. Explore the steps involved, the time pressure and the available alternatives.
Trust and perceived control
Customers may feel confident completing a payment but uncertain about recovering from a mistake. Study whether people understand confirmations, recognise unexpected requests and know where to seek help. Avoid assuming that frequent use means complete understanding.
Previous experiences
A delayed confirmation or unresolved complaint can influence future choices. Research should establish what happened, how the customer interpreted it and whether the eventual resolution restored confidence.
Merchant acceptance and support
The merchant’s experience matters too. Customers depend on acceptance being visible, instructions being clear and staff being able to respond appropriately when payment status is uncertain.
Device, connectivity and accessibility
Interface language, visual clarity, connectivity and device familiarity can shape the experience. These factors should be investigated with relevant participants rather than inferred from broad demographic labels.
Incentives and habitual use
Promotional offers may encourage initial use, but research should distinguish incentive-driven behaviour from lasting preference. Ask what customers choose when the offer is absent and why.
Research Methods That Reveal the Full Journey
Interviews with users, non-users and lapsed users
Recruit people with different payment habits. Ask them to describe a recent purchase, the method selected and the alternatives considered. Include people who tried UPI but stopped or use it only occasionally.
Behaviour-based questions are more useful than asking whether digital payments are generally convenient. They reveal the conditions under which convenience disappears.
Payment diaries
Short diaries can capture payment situations close to when they occur. Participants record the purchase context, method used and any difficulty, without sharing sensitive financial details. Compare routine purchases with exceptions to identify patterns that a retrospective interview may miss.
Surveys
Use surveys to assess how common specific experiences or preferences are within a defined sample. Specify the audience, recruitment method and limitations. An online-only sample may underrepresent people who face digital access barriers.
Usability testing
Test onboarding, payment selection, confirmation and help-seeking through safe prototypes or controlled demonstrations. Do not ask participants to disclose PINs, passwords or one-time passwords, and do not require real transfers to demonstrate ordinary interface tasks.
Journey mapping and operational analysis
Connect research findings with appropriately aggregated checkout and support data. Customer journey mapping research can help organise the stages before, during and after payment, including handoffs between customers, merchants and support teams.
A Practical Research Framework
Step 1: Choose the business decision
Define what the research needs to inform: reducing checkout confusion, improving onboarding, understanding low repeat usage or evaluating a new payment journey. Avoid collecting broad attitudes without a decision attached.
Step 2: Define meaningful user groups
Segment by behaviour as well as demographics. Frequent users, occasional users, customers who rely on another payment method and people who recently experienced a problem may provide different insights.
ResearchFox’s customer segmentation research guide explores how groups can be formed around needs and behaviour rather than assumptions alone.
Step 3: Capture the complete experience
Study the trigger, choice, payment attempt, confirmation and any follow-up. Record the difference between the system’s status and the customer’s understanding of that status.
Step 4: Prioritise the barriers
Assess frequency, severity and the ability of the business to address each issue. A relatively uncommon but highly distressing problem can deserve attention even when it affects fewer transactions.
Step 5: Test improvements safely
Evaluate clearer wording, status communication, accessible help and merchant instructions. Set success measures in advance, such as correct comprehension or task completion in a controlled test. Monitor unintended effects, including whether a simplified message creates misplaced confidence.
Example: Investigating Checkout Abandonment
Imagine a retailer notices customers leaving after selecting UPI. It would be premature to conclude that customers dislike the payment method.
Interviews might reveal uncertainty about switching between applications. Usability testing might uncover unclear return-to-merchant instructions. Operational data might identify a separate technical issue during particular checkout sessions.
These are hypothetical possibilities, not research findings. They illustrate why observation, customer accounts and system data should be considered together. Each explanation leads to a different intervention, and the evidence should determine which one is pursued.
Common Mistakes in UPI Research
- Measuring awareness without examining repeated use.
- Treating transaction activity as proof of customer satisfaction.
- Interviewing only digitally confident customers.
- Attributing every failed checkout to the payment interface.
- Collecting identifiable transaction details when they are unnecessary.
- Reporting changing payment rules, charges or limits without checking current official information.
Research materials should avoid requesting account credentials or exposing participants’ financial information. Use anonymised scenarios and collect only what the study needs.
How ResearchFox Can Help
ResearchFox’s business research capabilities can be a starting point for a brief covering payment choices, adoption barriers and customer experience questions. The brief should identify the relevant users, payment situations and decisions before selecting methods.
An actionable study explains which customer problems need attention and how to evaluate a proposed improvement, rather than producing usage percentages without context.
Frequently Asked Questions
What does UPI consumer behaviour research measure?
It can examine awareness, trial, frequency, payment situations, preferences, trust, barriers and responses to problems. The measures should reflect the specific decision the business needs to make.
Are transaction volumes enough to understand customers?
No. Activity data shows what occurred within the available dataset, but it may not explain motivation, confusion or why someone selected a different method. Qualitative research can help interpret those gaps.
Should a study include people who do not use UPI?
Yes, when adoption is part of the research question. Non-users and lapsed users can reveal barriers that a sample of active users would miss. Their experiences should be analysed separately where appropriate.
How can payment usability be tested safely?
Use prototypes, fictional information and controlled tasks that do not require financial credentials or live payments. Explain the study clearly, minimise personal data collection and establish appropriate handling of recordings and responses.


